Updated:
Haemonetics shares rose sharply in morning trading on Thursday, October 8, after CSL Plasma indicated it expects to transition all of its current U.S. plasma collection centers to Haemonetics equipment by the end of 2027. The update gives investors a broader potential deployment than the companies’ earlier supply agreement had specified, though it does not guarantee a particular purchase volume or revenue contribution.
Investing.com reported a 16.1% gain in morning trading and an intraday high of $120.72. Dow Jones reporting carried by MarketScreener also described a roughly 16% rise in premarket trading. The differing figures reflect different trading times; they point to a strong company-specific move following the rollout update.
From a limited agreement to a network-wide plan
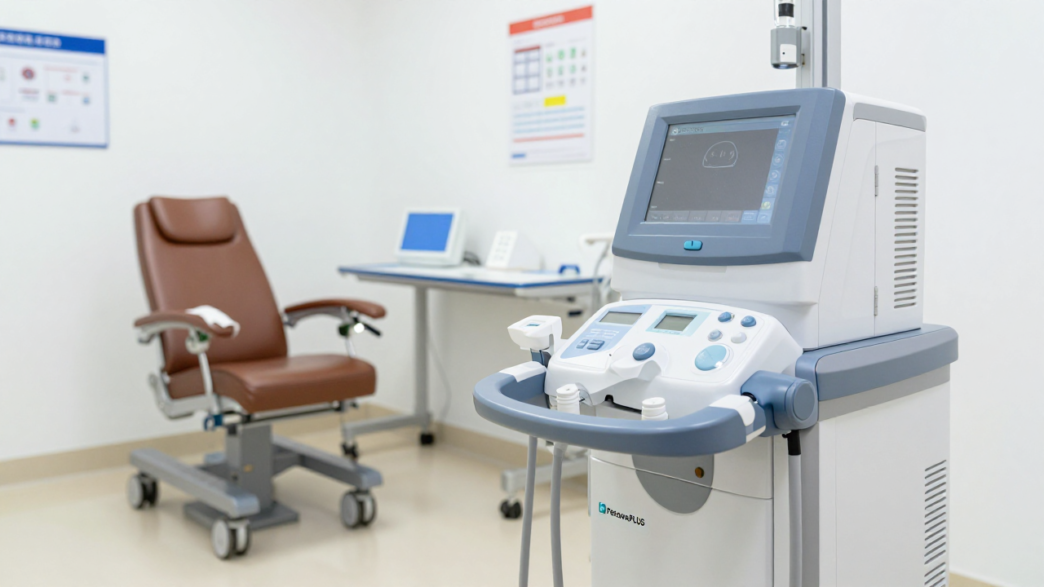
Haemonetics disclosed the supply agreement with CSL Plasma in August. Under its terms, CSL could use Haemonetics’ NexSys PCS plasma collection devices featuring Persona PLUS technology and buy related disposable products for use in the United States. The agreement was non-exclusive and included no minimum purchase commitments.
At the time, Haemonetics said CSL might transition a portion of its U.S. centers, while the scope and timing remained unsettled. The Oct. 8 update changed that expectation: Haemonetics said CSL currently anticipates the transition will cover all of its current U.S. plasma collection centers, with completion expected by the end of calendar 2027.
The shift matters because the earlier agreement left open how many centers would adopt the equipment. A plan covering the full existing network offers a larger potential deployment, but the filing does not turn that plan into guaranteed orders, specify the number of devices or disposables involved, or quantify resulting sales.
Company leaves guidance unchanged
Haemonetics said the rollout’s scope and timing remain subject to change under the supply agreement, and implementation details have yet to be determined. The company did not revise its previously issued fiscal 2027 guidance in response to the update.
It said it expects to discuss the anticipated effect of the agreement on fiscal 2027 results during its second-quarter earnings call in November. Until then, investors do not have company-provided figures for the expected revenue contribution, the pace of center conversions or the associated costs.
Recent results provide additional context
The CSL news arrived against a recent earnings backdrop that Investing.com described as stronger than analyst expectations. Haemonetics reported adjusted earnings of $1.14 per share for fiscal first-quarter 2027, compared with a cited consensus estimate of $1.09, and revenue of $339 million versus expectations of about $329 million.
Those results are separate from the CSL rollout and do not establish what the new deployment will add to future performance. The company’s decision not to update its outlook underscores that it has not yet provided a revised forecast incorporating the anticipated full-network transition.
What comes next
The immediate milestone is Haemonetics’ planned November earnings-call update on the agreement’s expected fiscal 2027 impact. The longer-term operational target is completion of the anticipated transition by the end of calendar 2027, but both the schedule and scope remain subject to change.
Investing.com also reported that BTIG raised its Haemonetics price target to $130 from $110 while keeping a Buy rating after the news. That is an analyst’s valuation view, not a company forecast or a guarantee of future share performance. The company’s next disclosure should provide more detail on expected financial effects; until then, the rollout’s actual contribution remains uncertain.