Updated:
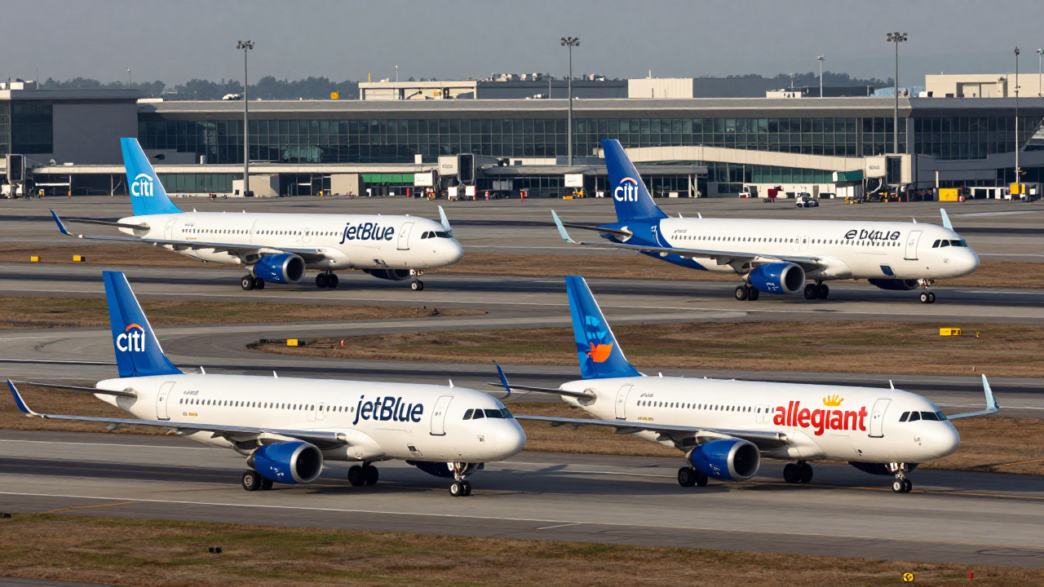
Citigroup upgraded JetBlue Airways to Neutral/High Risk from Sell/High Risk and placed Allegiant Travel on a 90-day positive Catalyst Watch, according to an October 6 report by Investing.com. The bank’s central message was that airline stocks may struggle to sustain a rally unless carriers pair strong demand with restrained capacity growth in 2027.
JetBlue and Allegiant shares rose 3.7% and 2.8%, respectively, in premarket trading following the report. The moves came as Citi reassessed the sector after airline stocks had retreated from summer highs, while warning that fuel costs and future seat supply remain important risks.
JetBlue upgrade reflects valuation, not a changed outlook
Citi’s upgrade of JetBlue was primarily based on valuation, the report said. With the shares near $4, analysts saw less downside than when they downgraded the airline above $6 about two months earlier. The rating change did not represent a broader improvement in the bank’s view of JetBlue’s competitive position.
Citi maintained that larger network airlines—described in its note as “supermajors”—were likely to continue outperforming legacy low-cost carriers. Its distinction matters because a lower share price may improve the perceived balance between risk and potential return without resolving operational or competitive challenges.
JetBlue’s latest publicly filed second-quarter investor materials reported an operating fleet of 296 aircraft as of June 30, 2026. That company filing provides operational context, but it does not establish a 2027 capacity plan; Citi’s concern, as relayed by Investing.com, was that sector-wide capacity growth could accelerate faster than demand and revenue growth can support.
Citi sees a capacity test for the entire sector
The bank’s analysts said airline demand had been strong, but shares had generally weakened even as fuel prices moved lower. Citi’s view, as reported, was that unit-revenue growth had likely peaked and would slow in 2027. The bank consequently forecast below-consensus 2027 results for most airlines it covers, while its estimates for 2028 exceeded consensus at Delta Air Lines, United Airlines, American Airlines and Allegiant.
Citi argued that airlines need to demonstrate conservative 2027 capacity plans—not simply describe demand as healthy—to support a lasting share-price recovery. Analysts considered capacity reductions underway but insufficient, and cautioned that low-single-digit growth exiting the fourth quarter could make a return to high-single-digit growth by mid-2027 more likely.
Fuel remains another qualification. Although the recent decline from summer highs had improved the sector’s risk-reward profile, Citi noted that fuel prices were near earlier highs and that airline stocks had not all fallen back to their previous lows. The bank therefore cautioned that the improvement in prospects might be less pronounced than share-price movements alone suggested.
Allegiant catalyst watch includes merger and investor-day events
Citi reiterated its Buy/High Risk rating and $156 price target for Allegiant while adding the airline to a positive catalyst watch for 90 days. The target implied about 100% upside from the share price used in the report; it is an analyst estimate, not a guaranteed return or company forecast.
The analysts identified Allegiant’s planned combination with Sun Country Airlines as a potentially significant strategic development and said they were positive on the company ahead of third-quarter results and an investor day expected in December. Allegiant’s 2025 annual report confirms that the company announced a definitive agreement in January 2026 to acquire Sun Country. The report does not establish whether or when the transaction will close, and the available material does not provide further detail about regulatory or shareholder milestones.
Allegiant’s second-quarter 2026 company materials described a schedule concentrated around peak leisure-travel periods. They reported that scheduled-service capacity was down 6.2% year over year in the quarter, while the company expected third-quarter revenue to increase approximately 16.5% against a combined airline-only comparison. Those reported figures offer recent context for Citi’s focus on capacity discipline, but do not guarantee future performance.
Delta’s outlook is an upcoming sector signal
Citi expected Delta, which was scheduled to report first among the major carriers on October 9, to provide the most conservative 2027 capacity outlook, according to Investing.com. The bank also expressed concern that United and American could have difficulty differentiating themselves from competitors in Chicago.
The key near-term question is whether airlines’ upcoming guidance demonstrates that capacity growth will remain controlled into 2027. Citi’s reported calls are assessments by bank analysts; the airlines had not, in the material reviewed, publicly confirmed the forecasts or adopted the bank’s characterization of the competitive outlook.