Updated:
South Africa’s private-sector business activity returned to contraction in September, as falling orders, higher fuel costs and supply delays weighed on companies. The S&P Global South Africa Purchasing Managers’ Index (PMI) fell to 49.0 from 50.5 in August, crossing below the 50-point mark that separates improving conditions from deterioration.
The October 5 survey reading marked the weakest performance in the index so far in 2026 and the first deterioration in three months. It is a measure of private-sector operating conditions, not an official calculation of gross domestic product (GDP), and should not be read as proof that the entire economy contracted during September.
New orders fell at their fastest pace in two-and-a-half years
Businesses reported that incoming new orders declined at the sharpest rate in two-and-a-half years. Survey respondents pointed to caution among businesses and consumers amid uncertainty about domestic and international conditions, as well as higher fuel prices.
Companies reduced activity for the first time in three months, and at the fastest pace since May. Weak demand was the main reason reported for the downturn, though firms also cited input constraints and delays that limited operations.
Export business offered a partial counterpoint: new export orders increased for a fourth consecutive month, and at a faster pace than in August. That improvement did not offset the broader decline in incoming work.
Fuel and logistics added to cost pressures
Higher fuel prices contributed to a sharp rise in businesses’ input costs during September. Overall cost inflation eased slightly from August, reflecting a softer increase in staff costs, but companies raised the prices they charged customers at the fastest pace since June.
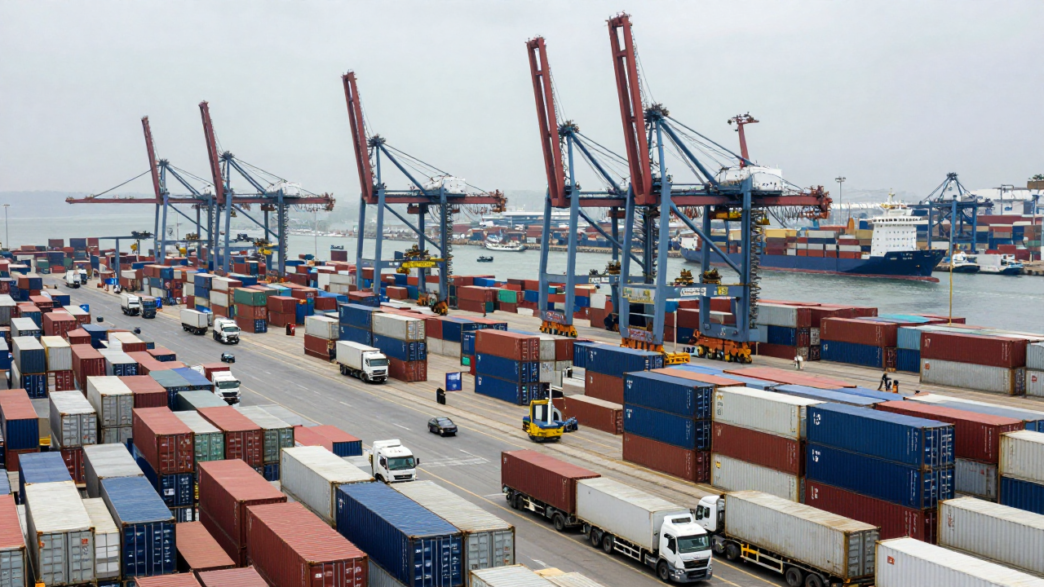
Supply-chain pressures also worsened. Suppliers’ delivery times lengthened to the greatest extent since February 2024, with surveyed businesses reporting container backlogs and delays at the Port of Durban. The report also identified shipping disruption and material shortages linked to conflict in the Middle East.
As order volumes weakened, firms trimmed input purchases and inventories. Stocks of purchases fell at their sharpest rate in a year and a half, a sign that companies were adjusting buying to subdued demand rather than building supplies.
Employment stayed broadly stable
Employment levels were relatively stable in September, continuing a pattern seen in August. The survey indicated that lower activity helped companies keep on top of outstanding work, rather than allowing backlogs to build.
Business expectations for the coming year improved to a four-month high. Firms expressed optimism about future demand and described expansion plans, with hopes that supply problems and fuel-price pressures would ease. The survey’s forward-looking responses reflect business sentiment, not a guarantee of stronger output.
PMI weakness follows a quarterly GDP contraction
The September survey adds to concerns about a fragile growth picture after official figures showed South African GDP contracted by 0.2% quarter on quarter in the second quarter of 2026, following growth of 0.4% in the first quarter. The Reserve Bank said in September that it still expected a second-half rebound and projected annual growth of 1.2%, while warning that risks were tilted to the downside.
The quarterly GDP figures and monthly PMI measure different things: GDP records economy-wide output, while the PMI summarizes survey responses from private-sector businesses. The September reading therefore signals worsening business conditions, but does not establish the size or direction of GDP for the month.
S&P Global collected the September PMI survey responses from September 10 to 28. The report presents business expectations and conditions during that period; it does not specify when the reported fuel or supply-chain pressures will ease. The next concrete measure of economic activity will come from subsequent official and survey releases.